AI Infrastructure Strains the Future
AI Infrastructure Strains the Future
The race to build AI is no longer just a software story. It is becoming a brutal contest over power, land, chips, water, talent, and political permission. For businesses, governments, and consumers, AI infrastructure now determines who can deploy the next generation of digital services and who gets priced out of the future. The latest reporting around this shift highlights a pressure point the tech industry can no longer gloss over: intelligence at scale needs physical scale. Every smarter chatbot, automated workflow, recommendation engine, and enterprise assistant depends on a widening stack of data centre capacity, GPU supply, and energy access. That makes the boom exciting, but also fragile. The winners will not simply be the companies with the flashiest models. They will be the ones that can secure the pipes, power, and trust needed to keep them running.
AI infrastructureis becoming a strategic bottleneck, not just a back-office technology concern.- Energy demand is now central to the
AIboom, forcing hard questions about grids, emissions, and local impact. - Chip access remains a power lever, with
GPUscarcity shaping which firms can compete. - Governments are moving from observer to referee as national security, jobs, and public services enter the debate.
- The next phase of
AIwill reward operational discipline as much as model innovation.
AI Infrastructure Is the Real Battleground
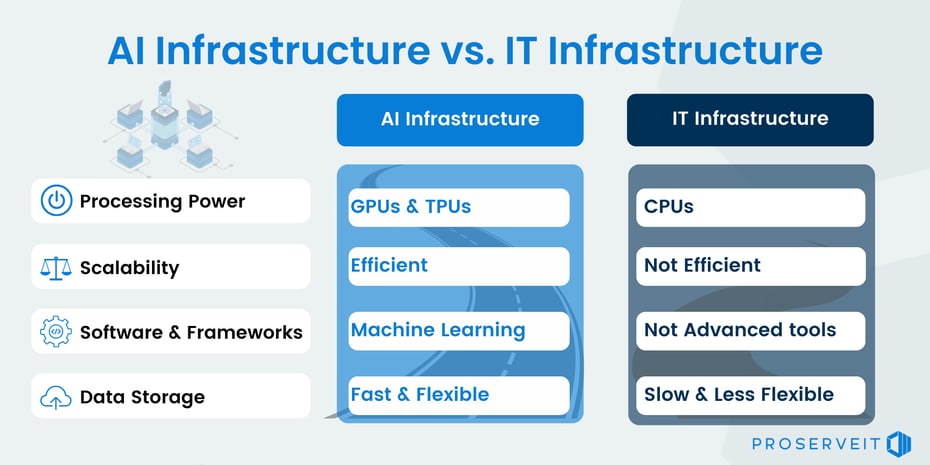
The early public story of generative AI was about demos. A prompt went in, a polished answer came out, and the interface felt close to magic. But behind that illusion sits an industrial machine. Modern AI systems require enormous clusters of specialized processors, high-speed networking, cooling systems, storage layers, and resilient access to electricity. That stack is what turns a research breakthrough into a consumer product or enterprise platform.
This is why AI infrastructure has become the most important layer in the technology economy. A company can have a brilliant model, but if it cannot afford training runs, inference capacity, or reliable cloud access, it cannot compete at scale. The market is starting to understand that model quality and infrastructure control are inseparable.
The defining question is shifting from \”who has the best model\” to \”who can afford to run intelligence everywhere, all the time.\”
That shift favors deep-pocketed technology giants, but it also creates openings for specialists. Firms focused on more efficient chips, smaller models, smarter cooling, and workload optimization are suddenly mission-critical. The infrastructure layer may look unglamorous, but it is where the next wave of leverage lives.
Why AI Infrastructure Keeps Hitting the Grid
The most immediate tension is electricity. Large data centre campuses can consume vast amounts of power, and the rise of AI workloads changes the shape of demand. Traditional web services scale steadily. Advanced AI training and inference can create intense, concentrated loads that test grid planning and local resilience.
Power Is Becoming a Product Feature
For years, users judged digital services by speed, price, reliability, and privacy. Increasingly, there is another factor: whether the service can scale responsibly. If an AI assistant is cheap because it shifts environmental and grid costs onto local communities, that bargain will not stay invisible for long.
Companies are responding with long-term energy deals, investment in renewables, and experiments with nuclear, geothermal, and advanced storage. But the gap between ambition and deployment remains wide. Clean power projects can take years to permit and connect. Data centre demand can arrive much faster.
Cooling and Water Are the Hidden Constraints
Electricity gets the headlines, but cooling is another pressure point. Dense GPU clusters generate significant heat. Air cooling is often not enough for the most powerful systems, pushing operators toward liquid cooling and more sophisticated facility design. In regions already facing water stress, that creates reputational and political risk.
Pro tip for enterprise buyers: when evaluating an AI vendor, ask about workload efficiency, energy sourcing, and infrastructure redundancy. These are not soft sustainability questions. They are indicators of cost stability and operational maturity.
Chips Still Decide Who Gets to Scale
The GPU shortage has become one of the defining stories of the AI economy. Advanced accelerators are expensive, supply-constrained, and strategically sensitive. This gives chipmakers unusual pricing power and gives the biggest buyers a structural advantage.
For startups, the constraint is existential. Access to compute can determine whether a product ships, whether a model improves, or whether a company gets acquired before it can become independent. For governments, chip supply is now part of industrial policy. For enterprises, compute costs can make the difference between a promising pilot and a failed rollout.
The Rise of Smaller, Smarter Models
Not every business needs the largest frontier model. In fact, many should avoid it. Domain-specific models, retrieval systems, and optimized inference pipelines can often deliver better economics and stronger control. This is where the market is becoming more sophisticated.
A practical AI strategy increasingly looks like a portfolio: use large models for broad reasoning, smaller models for repeatable tasks, and conventional software for everything that does not need probabilistic output. The companies that win will not be the ones that use AI everywhere. They will be the ones that know where it genuinely adds value.
AI Infrastructure Is Now a Political Issue
When a technology requires land, power, chips, and public trust, it inevitably becomes political. Local authorities want jobs and investment, but they also have to answer residents worried about energy costs, water use, noise, and environmental impact. National governments want domestic AI capacity, but they must balance innovation with safety, competition, and security.
This is a major change from the last software boom. A viral app could once scale globally with relatively little public infrastructure debate. AI at industrial scale is different. It looks more like telecoms, energy, and logistics: capital-intensive, regulated, and strategically important.
Regulation Will Shape the Buildout
Expect more scrutiny over where data centre projects are built, how much power they use, and what benefits they deliver locally. Also expect governments to link AI infrastructure to national competitiveness. Countries that cannot host or access sufficient compute may find themselves dependent on foreign platforms for critical services.
This raises a difficult question: should compute be treated like critical infrastructure? The answer is increasingly yes. Not every server farm is nationally vital, but the ability to train and run advanced AI systems is becoming central to healthcare, defense, education, finance, and public administration.
What Businesses Should Do Now
Executives should treat the infrastructure layer as a board-level issue. Buying an AI tool without understanding its compute economics is like signing a logistics contract without asking about fuel costs. It might work during a pilot. It can become painful at scale.
- Audit use cases: identify where
AIcreates measurable value and where conventional automation is cheaper and safer. - Track unit economics: understand the cost per query, document, image, or workflow before expanding deployment.
- Diversify vendors: avoid being locked into a single
cloud, model provider, or hardware-dependent workflow. - Demand transparency: ask suppliers about energy sourcing, uptime, data handling, and model governance.
- Plan for regulation: build compliance and auditability into
AIsystems before rules tighten.
The smartest companies will not pause experimentation. They will professionalize it. That means moving from scattered pilots to governed platforms, shared infrastructure, and clear accountability. It also means resisting the hype cycle. Not every problem needs a chatbot. Not every workflow should be handed to a model. But where AI works, it can compress time, reduce friction, and unlock new capabilities.
The Future of AI Infrastructure Will Be Uneven
The next phase of the AI boom will not arrive evenly. Regions with abundant clean power, strong grid planning, skilled labor, and supportive policy will attract investment. Areas with constrained infrastructure may struggle, even if they have strong universities or ambitious startups. That could redraw the map of the digital economy.
There is also a social dimension. If only the richest companies can afford cutting-edge AI, market concentration will deepen. If public institutions cannot access reliable and affordable compute, the benefits of the technology will skew toward private platforms. The infrastructure debate is therefore also a competition debate.
AIwill feel virtual to users, but its limits will be physical: power lines, chip fabs, cooling systems, and political consent.
The excitement is justified. AI can improve research, productivity, accessibility, and decision support across entire industries. But the skepticism is necessary too. A technology that demands so much from the physical world must prove it can create value beyond investor enthusiasm and benchmark wins.
The companies and countries that understand this first will have the advantage. The future will not belong only to those with the smartest algorithms. It will belong to those who can build intelligence responsibly, efficiently, and at scale.
The information provided in this article is for general informational purposes only. While we strive for accuracy, we make no guarantees about the completeness or reliability of the content. Always verify important information through official or multiple sources before making decisions.